Chapter 11 - The Truth That Included Me
My signature looked small beside the columns of invoices.
I had put it on the memo because Daniel said routine vendor renewals were getting stuck on my desk. At the time, the company was growing faster than our approval process. I remembered wanting our people to spend less time waiting for me.
The review team’s attorney waited while I read it again. The memo gave Daniel authority over vendor renewals and related implementation spending within approved budgets, subject to the usual controls. It did not name Marcus, Alder Point Advisory, or any of the other companies now under review.
“I signed this,” I said. “I let Daniel make spending decisions without checking closely enough how he was using that authority.”
Rebecca glanced at me, but she did not interrupt.
“That was my mistake,” I continued. “It wasn’t approval for invoices describing work that didn’t happen. I don’t know yet which services happened and which didn’t. I know I never intended this memo to replace a budget or the normal checks.”
The attorney wrote something down.
“We need all of that in the record,” he said. “Including what you didn’t check.”
“I understand.”
On the screen, Helena nodded once. She had insisted that the independent reviewers examine my conduct as well as Daniel’s. I had agreed. Hearing my own failure described plainly still made me want to defend myself.
The attorney turned the memo sideways and placed the first invoice below it.
“This one says ‘renewal implementation assistance,’” he said. “Assistance with whose renewal?”
No one had found an answer attached to the invoice. The company’s approved budget included renewals for systems our staff used, but the reviewer could not match that invoice to a named system, a work order, or an identified project lead. Other invoices used phrases like “advisory support” and “deployment coordination.” Their descriptions were broad enough to sound familiar. So far, their supporting files contained no work product.
“Does that prove they did nothing?” I asked.
“No,” he said. “It tells us what evidence we still need to seek. It also means Marcus can’t establish that this memo covered the invoices merely by calling the work ‘implementation.’”
A month earlier, I might have wanted him to say more. I wanted certainty, especially when uncertainty had my name on it. But the absence of a document was not proof of everything I feared.
Rebecca pointed to a highlighted line of the memo.
“Even genuine authority has a scope,” she said. “We’re testing whether these payments fell within it and whether the required controls were followed.”
I looked at the approval bearing my name in the separate payment record. The reviewer had found a session under my credentials associated with my work laptop. Daniel’s company account had opened the same vendor record seven minutes earlier. I had left my laptop in our unlocked home study that day. Those facts frightened me precisely because they did not yet answer who had used my account.
“I want my laptop examined thoroughly,” I said.
“It is being examined,” the attorney replied. “And you will have the findings when they’re ready.”
That was another boundary I had to live with. I could answer questions. I could not direct an investigation simply because its answer mattered to me.
Leah joined us by video from the finance office. She looked tired, but the papers beside her were marked in the careful handwriting I knew from years of budget meetings.
“I’ve checked the ownership records against the vendor files,” she said. “The documents we have link Marcus to Alder Point and the second recipient company. Kestrel connects to him through another company. We’re preserving the underlying records, not just my summary.”
The pending $280,000 request to Kestrel had not cleared. Its submitter was still unknown.
Leah held up another page.
“I also reconciled the party-related entries against their expense classifications. The staffing invoice was entered as a business-development event. The payment request uses the same invoice number and company code. I still can’t confirm whether that charge settled, was adjusted, or was reimbursed.”
“What about the equipment and video?” Helena asked.
“Entered for company payment. Their final payment status still needs tracing. The videographer’s order describes a company reception at the mansion, and his later edit request came from Daniel’s office.”
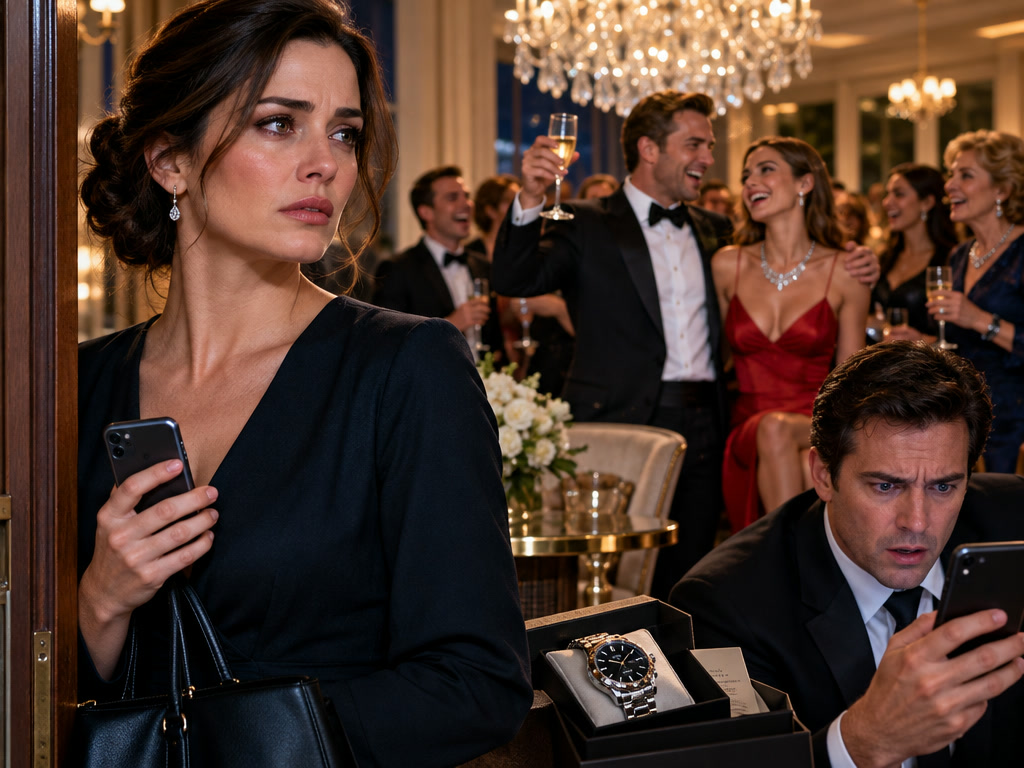
I could see the party again: Vanessa in my chair, Daniel lifting his glass, our guests laughing. For a moment, the people in the records ceased to be names on invoices. They were people who had stood in my home.
“And the necklace?” I asked.
“The company-card charge settled,” Leah said. “The jeweler’s identifiers match the necklace in the footage. We’re checking authorization and reimbursement. I won’t add it to the vendor-payment estimate without confirming how it’s counted.”
She had been more careful with the company’s money than I had been with its oversight. I wondered how many times she had questioned an entry and accepted an answer from Daniel because he was the CEO.
The attorney drew a line under the figure on Leah’s worksheet.
“Roughly $2.4 million in posted payments are flagged in the preliminary reconciliation,” he said. “That is not an established loss. Some work could yet be substantiated, and recovery is a separate question. The pending Kestrel request isn’t included. Neither are party charges whose settlement we haven’t traced.”
Helena leaned toward her camera.
“We have enough to explain why the memo isn’t an answer to every invoice,” she said. “We do not have grounds to pretend it was harmless. Claire signed it. Investors will want to know that, and employees deserve an honest account of what the company is doing now.”
My first thought was of payroll. The second was of the people who would hear “$2.4 million” and wonder if they should empty their desks.
“If we tell employees a loss has been confirmed, that would be wrong,” I said.
“Yes,” Helena replied. “So we won’t say that.”
“And if we say nothing?”
“Then they may hear a version of it from someone who has no reason to be careful.”
I thought of the anonymous warning Maya Sutton had received, accusing me of directing the payments and Daniel of trying to stop them. We still did not know who had sent it. Its existence had already shown how quickly an incomplete account could become someone else’s weapon.
Helena proposed two communications for the board to review: a direct briefing for investors with the preliminary figures and their limits, and a shorter employee update explaining Daniel’s suspension, the independent inquiry, temporary operating authority, and the status of payroll. Neither would identify a suspected wrongdoer the review had not established.
“I don’t want Vanessa’s name in an employee message,” I said.
“It doesn’t need to be,” Helena answered.
Vanessa had admitted that she knowingly coded Daniel’s birthday party as a client engagement. Her attorney had agreed to provide messages through the review team. What she had done mattered. It did not make her responsible for every questioned payment, and I would not let Marcus’s offer turn her into an answer to everything.
Leah’s phone chimed while we were discussing the wording. She checked it, then looked back at us.
“The payroll file was submitted,” she said. “I have a receipt that it reached the bank. That’s not confirmation of Friday deposits.”
I let out a breath I had not realized I was holding. It was one step, not a promise. There was no blanket hold on ordinary payments, but our available operating funds left little room for a surprise.
Helena asked Leah and the chief operating officer to prepare a short cash forecast for the board: wages, taxes, urgent obligations, and the nonessential payments they could defer. Leah said they had begun it already.
“What do you need from me?” I asked.
“An accurate account of the memo,” Helena said. “And your willingness to let the operating team show how the company functions while Daniel is suspended.”
“I can do both.”
Rebecca closed the invoice folder. For the first time that afternoon, no one was asking me to identify a signature or explain a decision. I looked at the company name printed across its cover. I had once thought trusting Daniel meant showing I believed in him. I had not seen how much I was asking everyone else to rely on that belief.
Helena arranged a call with Maya before we left the conference room. Maya had supported the company through difficult years. She was also the investor who had already seen the anonymous accusation, and she had questions.
I told her I had signed the delegation memo. The attorney explained its stated limits and the work still underway to test the invoices. Leah walked through the preliminary $2.4 million figure, careful to distinguish posted payments under review from a final loss. We did not give Maya a reassuring number for recovery because we did not have one.
When we finished, Maya was quiet.
“Will my money be needed to make Friday payroll?” she asked.
“We’re not asking you to cover it,” Leah said. “The file has been submitted, and current operating funds cover this run if ordinary payments process as expected. We’re monitoring it.”
“And next month?”
“We need a fuller cash forecast to answer that responsibly,” Helena said.
Maya turned to me.
“Claire, I can support an independent review. I can support a company that tells me its founder signed a memo she should have monitored more closely. What I can’t support is learning the estimate in pieces while everyone waits for a number that feels less frightening.”
“I won’t hide the estimate,” I said. “I won’t call it a final loss, either.”
“Good. Send the preliminary figure and its limits to the other investors now. Then show us who is authorized to operate, what spending stops, and how payroll and essential work continue if more payments are questioned.”
“We’re preparing that,” Helena said.
May you like



Maya’s expression did not soften.
“You have one day to present a credible plan.”







