Chapter 5: A Deal Put on Hold
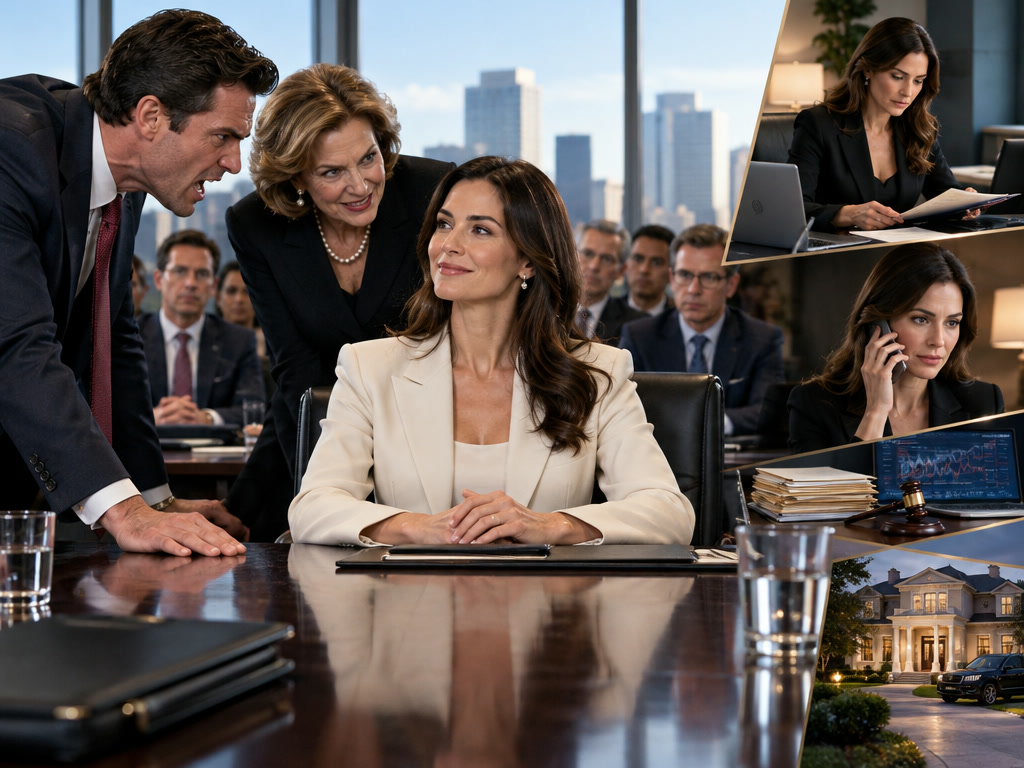
By the time Eleanor called, Margaret’s answer had settled into the room like dust.
“There’s nothing else to produce.”
I sat with the invoice review open on my laptop. Beside each payment was a date, an amount, and a blank space where a contract, deliverable, or other supporting record might have been. The blanks bothered me. They did not prove what had happened. They did tell me we needed to ask more questions.
Eleanor closed the folder in front of her.
“The audit team will document her response and continue the review,” she said. “We should keep the acquisition discussion separate from any conclusion about those invoices.”
“I agree.”
She studied my face.
“Tomorrow’s meeting will be difficult.”
“Because of the acquisition?”
“Because everyone will want an answer before the records can provide one.”
I shut the laptop. On the screen behind the invoice schedule was the acquisition proposal: nearly forty million dollars, months of work, and a future the company had been eager to announce. I had negotiated through setbacks and late-night revisions to get it this far.
I had also learned that wanting something badly did not make it safe.
The next morning, the acquisition team gathered in a conference room at headquarters. Their presentation was ready, but no one seemed eager to begin. David sat at the far end of the table, his expression calm in the way that often preceded an accusation. Eleanor took a seat beside me. Several directors joined in person, with others attending remotely.
The team’s lead adviser brought up a slide showing the transaction’s next steps.
“We need to pause before advancing,” she said. “The company has restricted funds, and the unresolved financial questions affect what capital is available and what liabilities may exist.”
David leaned back.
“The acquisition itself has nothing to do with those questions.”
“It depends on the company’s financial position,” she replied. “We can’t responsibly treat the transaction as if the restrictions and review don’t exist.”
“What exactly are you saying?” one director asked.
“That moving forward now would expose the company and its shareholders to uncertainty we can’t yet quantify.”
A director looked toward me.
“Can the company fund the transaction as planned?”
“We can’t responsibly confirm that today,” the adviser said. “Some funds are restricted. The lender’s application remains under review, and no completed loan or disbursement has been confirmed. We also don’t have a settled accounting of the exposure.”
The distinction mattered. The application was not the same as a completed loan. The review was not a finding. But neither was it something we could wave away because a deal was important.
David tapped his pen against the table.
“So we’re going to let an unfinished review kill a transaction we’ve spent months building?”
“No,” I said. “We’re going to keep the company from making commitments it can’t properly assess.”
He looked at me.
“You’re sabotaging the acquisition.”
The old instinct rose in me—to smooth the moment, to assure everyone that I could make the problem disappear if they would just give me enough time. I let it pass.
“I’m protecting the company’s ability to make an informed decision.”
“You froze access to funds and brought lawyers into every conversation. Now you want to call this caution?”
“I authorized restrictions after the review identified specific transactions requiring examination,” I said. “The lender has confirmed that the application is still under review. It has not confirmed a completed loan or a disbursement. Those are the facts we have today.”
I turned to the page in my binder where I had written the dates.
“The restrictions began after the bank raised questions about disputed activity. The $680,000 transfer is documented in the review. Margaret’s invoices are being checked against the available records. The lender’s application remains pending. We have not established who submitted the disputed authorization page.”
David’s jaw tightened.
“You’re making it sound like I’m guilty.”
“No,” Eleanor said evenly. “We’re distinguishing documented facts from conclusions that have not been reached.”
The room went quiet.
I looked at the directors, not David.
“We don’t preserve shareholder value by pretending uncertainty isn’t there. If the deal is sound, it should withstand a careful review. If it can’t wait for us to understand the company’s position, that is information we need to consider.”
The acquisition adviser lowered the presentation remote.
“The other side has not withdrawn,” she said. “But we shouldn’t ask them to proceed based on assumptions we can’t verify. They’ll need a clear account of the company’s controls and the status of the review.”
One of the directors folded his hands.
“What would that account require?”
“An independent review of the relevant financial controls,” Eleanor said. “A defined scope, preserved records, and a report that distinguishes what is confirmed from what remains unresolved.”
David gave a short, humorless laugh.
“And who decides what goes into that report?”
“The board should approve the scope and receive the report,” Eleanor said. “The review should be independent of the people whose conduct or decisions may be examined.”
His gaze moved around the table, searching for someone to challenge her.
I understood the fear beneath his anger. A careful report could complicate the story he had told employees and investors: that every decision had been made properly, that the company’s strength was unquestionable, that my concerns were personal rather than financial.
But I couldn’t let fear of embarrassment become the company’s policy.
A director asked the acquisition team to outline the consequences of pausing.
The adviser did. Some work could continue on a limited basis, she said, but the company should not make new commitments or represent that funding and liabilities were settled. Any further spending needed to stay within the restrictions already approved. She did not promise the other side would wait.
“So the deal could be lost,” David said.
“Yes,” she answered. “That is possible.”
He turned toward me.
“There it is. That’s what you wanted.”
I felt the sting of it, but not the doubt he wanted to plant.
“I wanted the company to survive beyond the announcement.”
For the next hour, the directors discussed the practical questions: which work could safely continue, what information the independent review would require, and how the board could keep oversight from becoming a fishing expedition. Eleanor emphasized the existing scope and the need to document each request. I did the same. We were not going to sweep through employee files or treat a missing document as proof of intent. We were going to examine the relevant records, preserve what existed, and report what we could actually establish.
When the discussion ended, the board agreed to hold the acquisition while the company obtained an independent controls review. No one declared the transaction dead. No one promised it would survive.
David pushed back his chair.
“You’ve turned a business decision into a public spectacle.”
“It was already a business decision,” I said. “That’s why the directors are here.”
He stared at me for a moment, then left without answering.
I stayed behind to help Eleanor gather the papers. My hand paused over the acquisition proposal. I remembered the first time I had pictured what this company might become—not as a monument to anyone’s ego, but as something stable enough to outlast us.
A pause could feel like a loss. Sometimes it was the only way to find out what was worth saving.
The directors had barely cleared the room when an assistant brought in a message from the prospective investors. Their representatives had reviewed the company’s update and would not proceed with any future commitment until they received an independent controls report.
I read the sentence twice.
May you like



The deal was still possible, but the next move no longer belonged to a presentation or a promise.
It belonged to whatever the independent review found.







