Chapter 13: The Price Sarah Won’t Demand
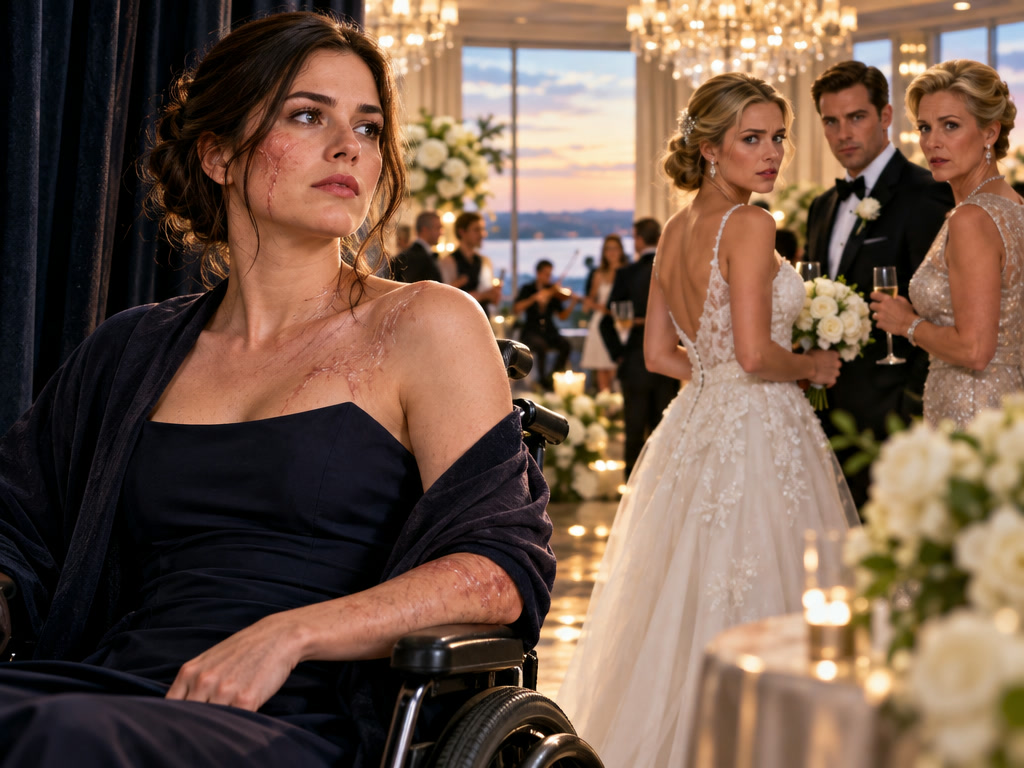
My attorney opened the envelope without disturbing the papers inside more than necessary. She checked the delivery record first, then arranged the documents across the library table in small, orderly stacks.
Martin stayed by the door. He didn’t sit until she invited him to, and he didn’t offer another summary.
That mattered to me.
For the next several minutes, the reception became a muffled soundtrack: a glass set down, a chair shifted, the quartet beginning a song and stopping before the melody found its feet. Inside the library, my attorney read each page aloud when it contained a number or a notation that could change the meaning of another page. I followed along on my phone, enlarging the scanned copies.
We started with the account schedule.
The same payment appeared there as received. In the history we’d seen earlier, it had no corresponding credit.
My attorney placed the schedule beside the newly delivered cash-receipt log.
“This shows the entry was recorded on the company’s side,” she said. “But we still need to compare the date and the terms in the governing documents before we say how it should have been applied.”
Martin nodded.
“Understood.”
The next page was an internal transfer record. A code had been left blank when the account information moved between systems. The receipt had gone into an unapplied-items queue instead of appearing in the payment history.
My shoulders tightened despite myself.
“Does this establish why the records didn’t match?” I asked.
“It gives us a documented explanation for the mismatch,” my attorney said. “It does not, by itself, establish the payment’s contractual treatment or the loan’s status.”
She made a note in the margin, then added a second note beside it: independent verification required.
Martin looked at the paper rather than at me.
“Our people have been trying to reconcile that transfer for weeks,” he said. “We received the money. The problem was where the system placed it afterward.”
“Is there a source record for the receipt?” my attorney asked.
Martin pointed to the next stack.
“Bank confirmation, batch log, and the month-end reconciliation. They’re all in there.”
She found them and checked the dates against the schedule. I watched her compare the entries. The confirmation supported that money had been received. The batch log showed it had been placed in the holding queue. The reconciliation showed that it had later been moved out of that queue.
But not every document answered the same question.
The receipt wasn’t the same as a complete account history. A posted transaction wasn’t automatically proof of how the loan terms treated it. And none of the papers told us whether other obligations were current.
The records made the mismatch less mysterious. They did not make the larger question disappear.
My attorney closed the file and left her finger resting on the page.
“This is a material explanation,” she said. “It is not a final accounting. A neutral professional should compare the source records to the loan documents and confirm the proper application.”
Martin looked as though he’d been holding his breath.
“Agreed,” he said. “The board doesn’t want to call it resolved until it has been verified.”
“What did the board ask you to do?” I asked.
“To keep the review moving, but not to make findings before the independent comparison. They want to protect the company’s operations while the records are checked.”
“Then we should write down exactly what that means.”
My attorney took out a draft framework. It was short enough to read at a glance, but every sentence had been weighed. The standstill remained limited to the estate loan and ran only through five o’clock the following day. It did not forgive debt, change the loan, or declare anyone in default. The independent reviewer would be chosen jointly, with access to the source records and the governing documents. Any report would go to both sides at the same time.
There were protections for employees, too: normal payroll and ordinary operations were to continue during the review, and no employee could be penalized for providing records or answering questions honestly. Documents were to be preserved. Business communications about the loan would go through counsel.
Nothing in the draft gave me a private payment, an ownership stake, or a personal benefit.
My attorney slid it toward Martin.
“Those are proposed protections,” she said. “They don’t decide the ultimate terms. They preserve a fair process while the review happens.”
Martin read slowly. When he finished, he passed the draft back to her.
“I can take this to the board tonight. I expect they’ll continue negotiations on that basis, contingent on independent verification and these protections for the people affected by the review.”
“Not approval of a final agreement?” I asked.
“Not yet. The board needs the verified records before it approves anything beyond the temporary standstill.”
It wasn’t a rescue. It wasn’t a threat. It was the next careful step, which was all I’d asked anyone to take.
“Then that’s what the draft should say,” I told my attorney. “No one should leave this room thinking the loan is settled.”
She added the sentence.
Martin glanced through the open doorway, toward the ballroom.
“The staff still thinks you asked to be placed behind the curtain,” I said. “They shouldn’t be left with that impression.”
“I’ll speak with Dana,” he replied. “We can correct the event file and make sure the staff understands that the main-room seating was available.”
“Correct it accurately,” I said. “Don’t turn it into a story about me wanting special treatment.”
“I won’t.”
There was one more point I wanted recorded—but not in the loan agreement.
“If Whitmore Development or one of its agents manages future events at the estate, I want a written accessibility process for seating and guest requests,” I said. “The coordinator had an accessible place ready. The problem was that someone chose to override it.”
“Would you want that included as a condition of the standstill?” Martin asked.
“No. It’s separate. I’m not trading loan terms for basic access, and I’m not using my position to demand a personal favor.”
My attorney made a separate note, outside the framework.
I looked toward the ballroom. Emily stood near the microphone stand, her hands folded at her waist. She hadn’t come to the library or sent anyone after me. I couldn’t tell whether she was waiting for a chance to speak or trying to give me the space I’d asked for.
Either way, she hadn’t asked me to make her feel better.
That was the first useful thing the apology had done.
The library door opened. Preston came in, followed by Emily. She stopped several feet behind him.
“Martin,” Preston said. “Has the board decided?”
“They’ve agreed to continue negotiations, subject to independent verification and the protections in this draft.”
Preston looked at the papers spread across the table.
“And the mismatch?”
“The records show why the payment appeared in one system but not the other,” my attorney said. “The independent reviewer still needs to confirm the proper application against the governing documents.”
“So you’re not saying we missed a payment.”
“We are not making a finding about the loan’s status tonight,” she replied. “That’s the point of the review.”
Preston’s gaze shifted to me.
“You could make this easier.”
“For whom?”
“For everyone. You could tell the board you won’t interfere while we sort it out.”
“I haven’t interfered. I asked for records and agreed to a temporary, limited standstill.”
“You control the debt.”
“Hale controls nearly sixty percent of Whitmore Development’s debt,” I said. “That is not the same as owning the company, and it doesn’t make an unverified account history conclusive.”
Preston pressed his lips together. Emily didn’t move.
Martin placed the draft framework on the table between us.
“No one is asking Sarah to decide the whole matter tonight,” he said. “This document gives both sides an independent review and protects the people who could be affected while it happens.”
Preston read the first page. His eyes stopped at the paragraph naming the neutral reviewer and the one requiring both sides to receive the findings simultaneously.
“Who chooses this reviewer?” he asked.
“Both sides,” my attorney said.
“And Sarah sees everything?”
“Both sides receive the same materials at the same time,” she answered.
“What about her oversight role?”
I studied him. “My role is not to run your business. The reviewer is independent.”
“That isn’t what I asked.”
My attorney didn’t answer for me.
I said, “I’ll make sure Hale follows the written process. I won’t tell the reviewer what to conclude, and I won’t decide the loan status without the records.”
Preston looked down at the last page. A line marked where the company’s representative could acknowledge the process—not agree to a final loan modification, not confess wrongdoing, only confirm that the records would be preserved and the review protections honored.
Martin turned the page toward him.
“If we proceed, I need your signature on the acknowledgment as the family’s representative,” he said. “The board can consider the framework, but it needs a clear commitment from the people supplying the records.”
Preston picked up the pen.
May you like



For a moment, I thought he might read the page again and sign. Instead, he set the pen down beside it.
“I won’t sign this while Sarah has oversight,” he said. “If she gives up that role, then we can talk.”







